Insurance Claims
Flood Damage Claims: Find a Public Adjuster in NJ & NYC
Flooded by storm surge, river or heavy rain? Get matched free with a licensed public adjuster for flood claims in New Jersey and New York City.
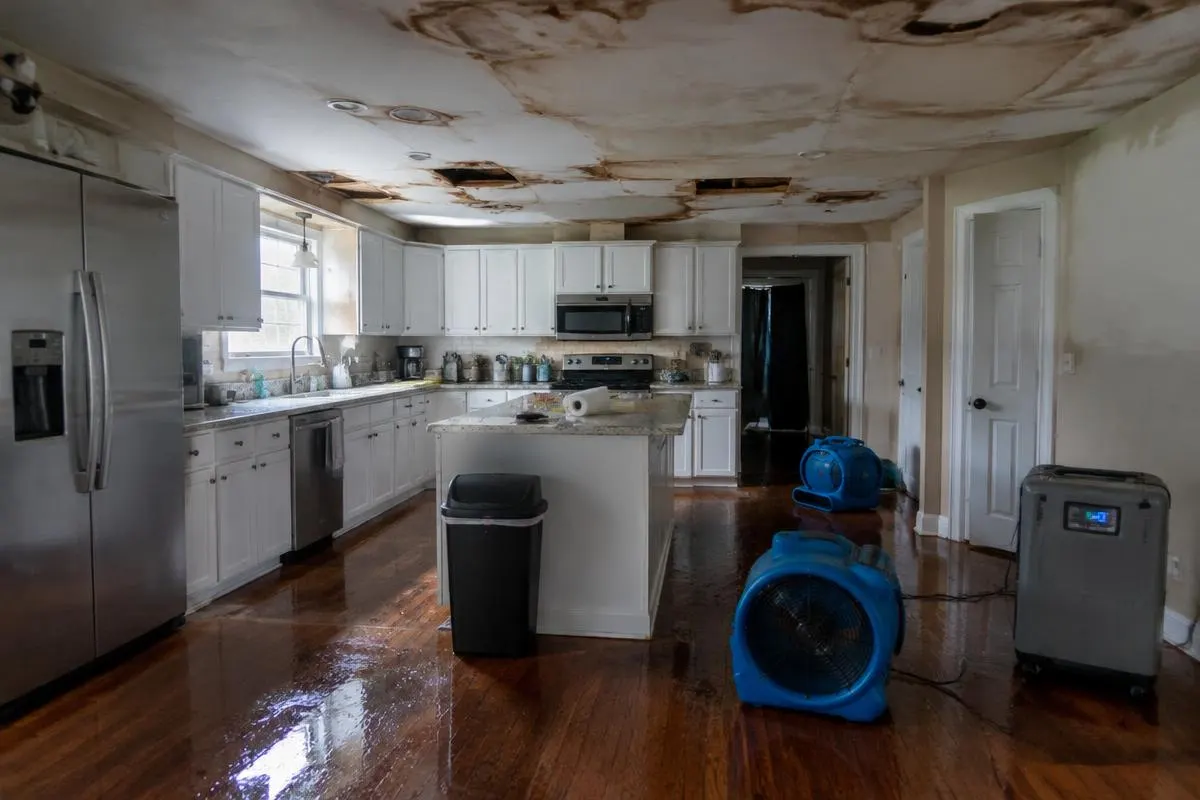
Flood damage — rising water from storm surge, overflowing rivers or flash flooding — is excluded from standard homeowners policies and is typically covered only by a separate flood policy through the National Flood Insurance Program (NFIP) or a private flood insurer.
Flood policies have strict rules, specific coverage limitations for basements, and firm deadlines for submitting a signed proof of loss. Many homeowners don't learn these rules until after a flood. The public adjuster you're matched with can help you meet deadlines, document the loss and pursue everything your flood policy allows.
Common reasons these claims get underpaid or denied
- Proof-of-loss deadlines are missed.
- Basement contents and finishes are excluded under flood policy limits.
- Damage is attributed to earth movement or pre-existing conditions.
- Contents values are depreciated heavily.
- Wind damage is wrongly assigned to the flood policy (or vice versa).
How a public adjuster helps with flood damage claims
The public adjuster you're matched with will:
- Tracks and meets flood policy deadlines, including proof of loss.
- Documents structure and contents damage thoroughly.
- Separates wind and flood damage when both policies apply.
- Reviews NFIP or private flood policy provisions.
- Negotiates with the flood carrier for full available benefits.
What to do right after a flood
- 1Wait until it's safe and authorities allow you back in.
- 2Photograph water lines on walls and all damaged property.
- 3Remove standing water and wet materials to limit mold.
- 4Keep samples of flooring, carpet and drywall where possible.
- 5File with your flood insurer promptly and note the proof-of-loss deadline.
- 6If you also have wind damage, file a separate homeowners claim.
Flood Damage claim FAQs
Get matched with a licensed public adjuster
Tell us about your loss and we'll connect you with an independent, state-licensed public adjuster who handles your type of claim. Free to use, no upfront cost.
- ✓ 100% free match, no obligation
- ✓ Licensed NJ & NY public adjusters
- ✓ No recovery, no fee
Public adjusters are typically paid a percentage of the claim payment under a written contract you sign with them. Public Adjuster Finder does not charge property owners.
Prefer to talk?
(908) 777-2257Public Adjuster Finder is not a public adjusting firm, law firm or insurance company. We connect property owners with independent, state-licensed public adjusters. Results vary by claim and policy; no settlement outcome is guaranteed.